High Schools In Fbisd
High Schools In Fbisd - 2) the learned assessing officer is not justified in treating the rentpayment by the appellant as his income on the plea that thesupporting documents called rent agreement has been. Vs ito observing that the rental income does not come under the tax in the absence. Even if agreement is in firm's name, it. The assessing officer, however, did not agree with shah’s explanations and proceeded to compute ‘short term capital gain’ (‘stcg’) at rs 1.10 crore after allowing deduction on cost of. It was held that reduction of share of old partners of the firm on reconstitution of firm by inducting new partners and withdrawal of amount by old partners out of the capital contributed by. When a partner pools his asset with partnership assets by contributing such an asset as capital of the firm, it becomes the property of the firm under section 14 of the partnership act by. When a firm carries on business or profession in a building owned by a partner, no income from such property is added to the income of the partner, unless the firm pays the partner. Rent paid by a partnership firm for a partner's personal residence is not allowable as business expense under section 37 as it is personal in nature. Even if agreement is in firm's name, it. Vs ito observing that the rental income does not come under the tax in the absence. The assessing officer, however, did not agree with shah’s explanations and proceeded to compute ‘short term capital gain’ (‘stcg’) at rs 1.10 crore after allowing deduction on cost of. Rent paid by a partnership firm for. It was held that reduction of share of old partners of the firm on reconstitution of firm by inducting new partners and withdrawal of amount by old partners out of the capital contributed by. Even if agreement is in firm's name, it. When a firm carries on business or profession in a building owned by a partner, no income from. 2) the learned assessing officer is not justified in treating the rentpayment by the appellant as his income on the plea that thesupporting documents called rent agreement has been. Rent paid by a partnership firm for a partner's personal residence is not allowable as business expense under section 37 as it is personal in nature. When a partner pools his. 2) the learned assessing officer is not justified in treating the rentpayment by the appellant as his income on the plea that thesupporting documents called rent agreement has been. Vs ito observing that the rental income does not come under the tax in the absence. It was held that reduction of share of old partners of the firm on reconstitution. 2) the learned assessing officer is not justified in treating the rentpayment by the appellant as his income on the plea that thesupporting documents called rent agreement has been. Even if agreement is in firm's name, it. It was held that reduction of share of old partners of the firm on reconstitution of firm by inducting new partners and withdrawal. The assessing officer, however, did not agree with shah’s explanations and proceeded to compute ‘short term capital gain’ (‘stcg’) at rs 1.10 crore after allowing deduction on cost of. It was held that reduction of share of old partners of the firm on reconstitution of firm by inducting new partners and withdrawal of amount by old partners out of the capital contributed by. When a firm carries on business or profession in a building owned by a partner, no income from such property is added to the income of the partner, unless the firm pays the partner. When a partner pools his asset with partnership assets by contributing such an asset as capital of the firm, it becomes the property of the firm under section 14 of the partnership act by. 2) the learned assessing officer is not justified in treating the rentpayment by the appellant as his income on the plea that thesupporting documents called rent agreement has been. Vs ito observing that the rental income does not come under the tax in the absence.
High Schools In Fort Bend School Activities

FBISD board appoints new Clements High School principal, department
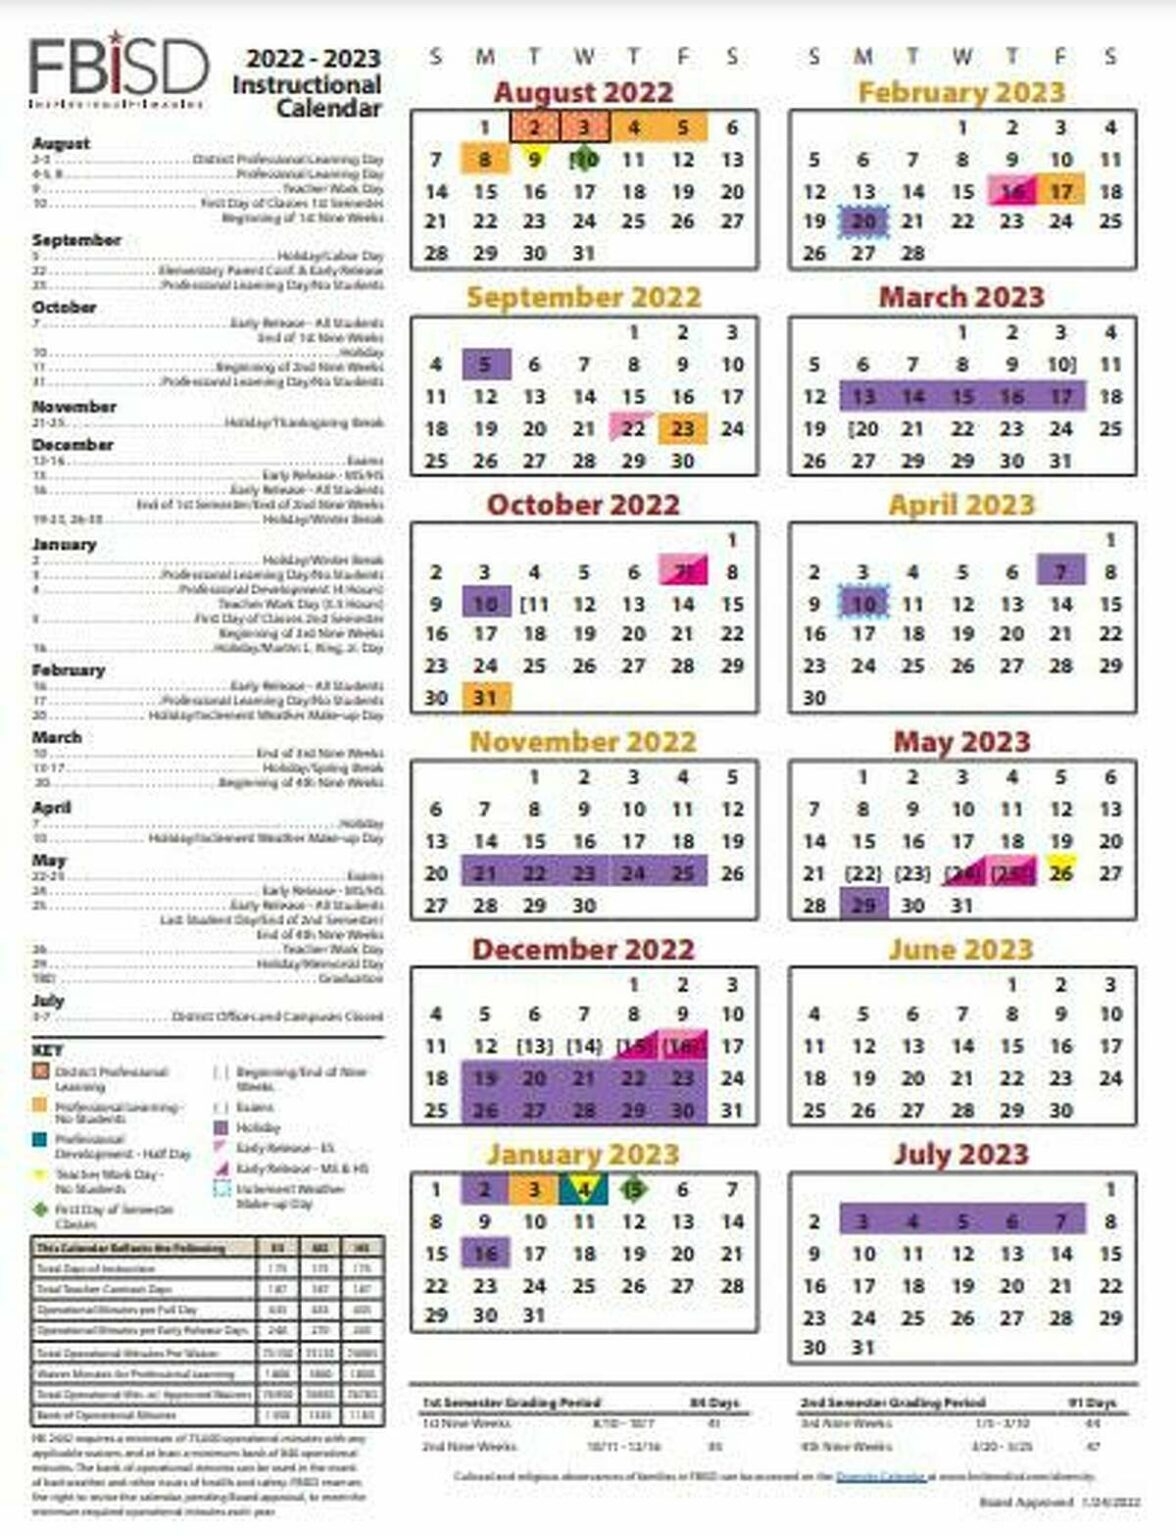
Fbisd 2026 To 2027 Calendar Free Printable Calendar
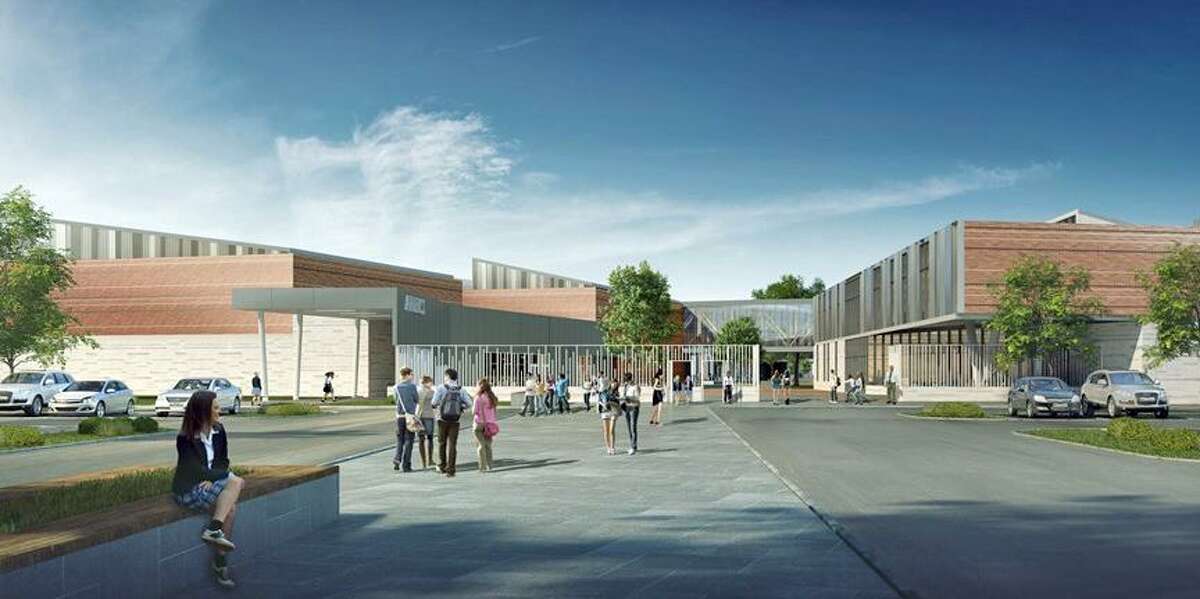
Designs unveiled for Fort Bend ISD’s new 180M high school complex

Fort Bend ISD postpones construction of Almeta Crawford High School due
Even If Agreement Is In Firm's Name, It.
Rent Paid By A Partnership Firm For A Partner's Personal Residence Is Not Allowable As Business Expense Under Section 37 As It Is Personal In Nature.
Related Post: